 Dubai Weekly
Nvidia 's ( NVDA -0.74% ) graphics processing units (GPUs) are the foundational hardware that is powering the artificial intelligence (AI) revolution. Along with its leading position in advanced GPUs for AI , the company is also building its position in central processing units (CPUs) and other hardware used in data center tech stacks. As a result of very strong demand for its AI-focused hardware products, the company made an unprecedented move with its latest quarterly report: It issued guidance for the subsequent fiscal year.
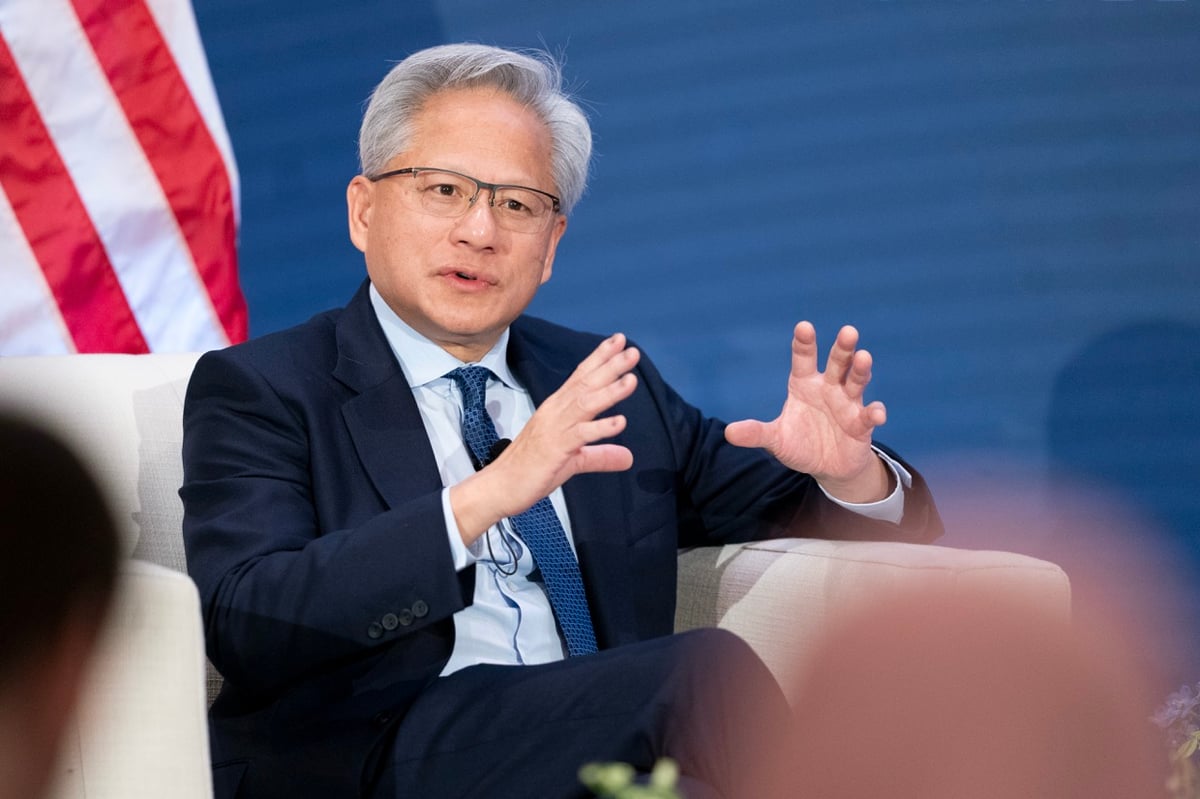
CEO Jensen Huang cited having "a lot greater visibility" into its demand outlook as the reason for the move. Does this mean that Nvidia stock deserves to trade at premium valuation? Image source: Getty Images.
First things first Nvidia stock has risen roughly 27% over the last year, and the AI hardware leader currently has a market capitalization of $5.77 trillion. Meanwhile, the company has a forward price-to-earnings (P/E) ratio of roughly 25.6. While Nvidia's forward P/E ratio represents a premium compared to the S&P 500 index average's forward P/E of roughly 19, that doesn't necessarily mean that the company is valued at a premium compared to its own growth.
In fact, there's a solid case to be made that Nvidia could actually still be significantly undervalued based on the rate at which it's expanding earnings. Premium Feature Moneyball Superscore 95 /100 Today's Change ( -0.74 %) $ -1.77 Current Price $ 237.47 Nvidia has a forward P/E value that looks high compared to the S&P 500 average, but the semiconductor company is growing earnings faster than nearly every other business in the index. Given that Nvidia's business is already highly scaled and commands the largest market capitalization of any company in the world, this is incredibly impressive.
Nvidia's growth outlook suggests the stock could have room to run In the second quarter of the company's 2027 fiscal year, which ended July 26, Nvidia's non-GAAP (adjusted) earnings per share increased 120% on the strength of a 106% increase for revenue. Meanwhile, the company's midpoint guidance for sales of roughly $108 billion in the current quarter suggests year-over-year growth of roughly 89% in the period. Crucially, the GPU frontrunner is guiding for its gross margin to remain very strong.
Next fiscal year, Nvidia expects annual sales growth of roughly 70% and continued strength for gross margins -- a bold forecast that Huang said is made possible by greater visibility on the demand outlook. With forecasts for that level of sales growth and guidance for a gross margin between 72% and 73%, there's a good chance that Nvidia will record growth for adjusted earnings per share above 70% in fiscal 2028. With that level of earnings growth seemingly on the horizon, Nvidia stock may actually deserve a much higher valuation multiple than it currently commands.
Keith Noonan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Nvidia. The Motley Fool has a disclosure policy .
Source: The Motley Fool