 Dubai Weekly
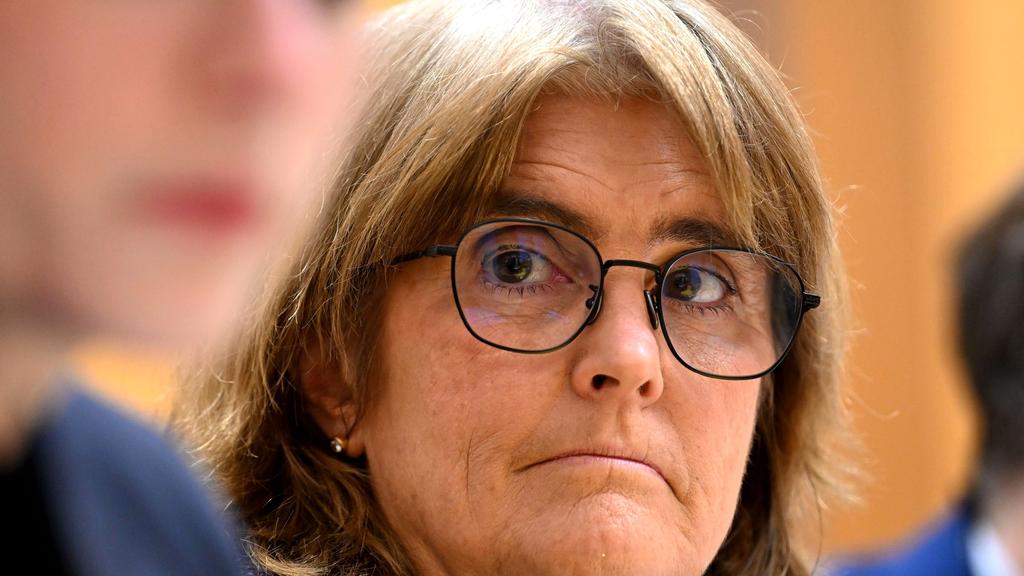
RBA Governor Michele Bullock is now under massive pressure to hike the cash rate target. Picture: NewsWire / Martin Ollman Two of Australia’s biggest banks have slapped on a double rate hike within days of each other as fears over escalating mortgage costs rampage across the country ahead of RBA’s expected increase. Commonwealth Bank put in the biggest individual hike this month following the footsteps of Westpac just days before, placing even more pressure on the Reserve Bank to act as inflation – with ANZ also projecting rates will hit GFC-era highs before Christmas .
Cash rate forecasts. Source: RBA Canstar.com.au data insights director, Sally Tindall, said “Australia’s biggest bank has delivered a hefty blow to its fixed rates, jacking up its 2-year loan by 0.48 percentage points – nearly twice the size of a standard cash rate hike”. “A 0.48 percentage point increase isn’t a tweak, it’s a clear signal Australia’s biggest bank is bracing for higher borrowing costs ahead.” CBA head of Australian economics Belinda Allen said “inflation remains too high and households are having to devote a larger share of wallet to fuel ...
The path of the oil price from here given already too high inflation does place the RBA in a difficult position. We now expect the RBA to hike in September, a meeting earlier than our previous November call.” “The risk sits with a follow up hike depending on upcoming inflation prints and the path of the Middle East conflict and oil prices.” Westpac had hiked owner-occupier fixed home loan rates by as much as 0.45 percentage points – with its chief economist Dr Luci Ellis warning of a huge shift in forecasts, joining NAB to name September for the next increase, plus a “follow-up” in the weeks to come. The changes follow similar moves by NAB and ANZ last week, who put in increases of up to 0.20 percentage points.
Ms Tindall said 16 lenders have now increased at least one fixed term in September, including CBA, Macquarie, BankSA, Queensland Country Bank, Westpac, ING, Great Southern Bank, Aussie, NAB, St George, Bank Australia, Firstmac, ANZ, Bank of Melbourne, Qudos Bank and loans.com.au. Lowest 1 yr fixed vs. lowest variable, $600,000 debt. Canstar’s database shows the lowest fixed rate from a big four bank now 6.49 per cent for a 1-year term from ANZ, and a 2-year term from both NAB and ANZ.
Ms Tindall said “anyone considering a fixed rate would do well to look beyond the majors and take their time weighing up their options. Yes, the window on fixed rates starting with a 5 could be closing but when it comes to big financial decisions, it’s important to do your due diligence.” “While in theory, based on current cash rate forecasts, fixing for one year could potentially see you pay less interest. However, the cash rate isn’t set in stone and a lot of borrowers are likely to ride it out.
If that’s you, make sure you’re on a competitive rate.” The market has gone ballistic on rates since RBA Governor Michele Bullock told the House of Representatives economics committee in Canberra Friday morning that inflation triggers were actively “materialising” across the economy – questioning whether the 75 basis points of rate hikes delivered so far this year would be “sufficient” to get prices under control. Canstar’s database still has lenders with fixed rates starting with a 5. “I recognise that higher interest rates are difficult for Australians with mortgages who are also facing cost-of-living pressures.
But reducing inflation is essential,” she said. RBA’s next cash rate decision is in less than a week on Tuesday September 29. Ms Tindall said there are still seven lenders on the Canstar database offering fixed rates starting with a 5 to owner-occupiers.
The lowest rate on the Canstar database is now 5.79 per cent. Canstar analysis found a borrower with a $600,000 mortgage and 25 years remaining could save $776 in interest over the next 12 months by opting for the lowest 1-year fixed rate rather than the lowest variable rate. That was based on CBA’s forecast of a rate hike this month followed by two cash rate cuts from August 2027 – assuming banks pass on variable rate changes – and does not factor in any extra repayments or fees.
Source: realestate.com.au